 Starcycle
Guide
Closing your business? Starcycle runs the shutdown with you.
Get startedIf your company still owes money as it closes, you'll hear liquidation and bankruptcy in the same week, often as if they meant one thing. Liquidation means selling your business's assets and using the money to pay what it owes, and it can happen with or without a court. Bankruptcy is a federal court case, and only some bankruptcy cases end with the business liquidated.
The two paths differ on who runs the process, how your creditors get paid and what's left for you as an owner.
No: liquidation is the act of turning a business's assets into cash and paying its debts in order, while bankruptcy is a case filed in federal bankruptcy court. Your company can liquidate under state law without going near a courtroom. One kind of bankruptcy, Chapter 7, is a liquidation, and another, Chapter 11, usually keeps the business running.
The two words overlap because the federal courts use one to name the other. The Bankruptcy Code titles Chapter 7 "Liquidation", and the U.S. Courts describe it as a court-supervised procedure in which a trustee takes over the assets, reduces them to cash and makes distributions to creditors. So "bankruptcy liquidation" is a real thing, and it's one of several ways your business could be liquidated.
Part of the confusion comes from timing. You meet these words while outstanding debts, vendor payments, tax obligations and final payroll all demand attention at once, and while you're ending something you built. Under that pressure, a founder might think "liquidation" means the business has already gone bankrupt, or believe bankruptcy must occur whenever a business closes, even if there's enough money to pay what is owed. Neither assumption is true: a company can liquidate under state law with no court involved, and a bankruptcy case starts only when a petition is filed.

Liquidation is the process of selling what a business owns, paying its creditors from the proceeds and passing anything left to the owners. It's a stage of closing a company, and it can be run by you and your co-owners under state law or by a trustee in a bankruptcy case.
The assets are whatever your business can turn into cash: inventory, equipment, vehicles, money customers still owe you, and intellectual property such as a domain or a codebase. State law sets the order the money goes out in, and Delaware makes a clear example. A dissolved Delaware corporation pays or makes provision for its claims, and any remaining assets go to the stockholders. A Delaware LLC that's winding up distributes its assets to creditors first and to members after that. Your own state's business statute carries its version of the same rule.
If you want the order of work once your company goes into liquidation, our guide to the company liquidation process lists the steps.
A voluntary liquidation starts with you and the other owners. You vote to close, the company stops trading, sells its assets and pays its bills, and whatever remains is distributed under your operating agreement or bylaws. You'll see this called a solvent liquidation when the assets cover every debt. Retirement, a sale that didn't happen and a product that never found its market can all end this way. No court is involved. A founder who sells a software company's remaining assets, pays every vendor and employee, files the final tax returns and distributes what's left to the shareholders has liquidated the company. It took no bankruptcy filing, and no creditor forced the closure.

An involuntary liquidation starts with someone other than you and your co-owners. In bankruptcy, the U.S. Courts note that creditors holding claims against a business can file an involuntary Chapter 7 petition under certain circumstances. Insolvency, where debts exceed the assets available, can lead to talk of bankruptcy, though a case opens only when the business or its creditors file a petition. That's a different event from a state ending a company's registration for missed reports or taxes, which is covered in our guide to involuntary dissolution.
Obligation tracking, document organization, and stakeholder coordination — in one platform, in the right order.
Get my shutdown planBankruptcy is a legal case in a federal court, governed by the Bankruptcy Code, which the U.S. Courts call the uniform federal law for all bankruptcy cases. If your business files, it gets a pause on most collection activity while its debts are either paid from a sale of its assets or restructured under a court-approved plan.
Cases are heard by a bankruptcy judge in one of 90 bankruptcy districts, though much of the work is administrative and happens away from the courthouse. In the Department of Justice, the U.S. Trustee Program supervises how cases are administered.
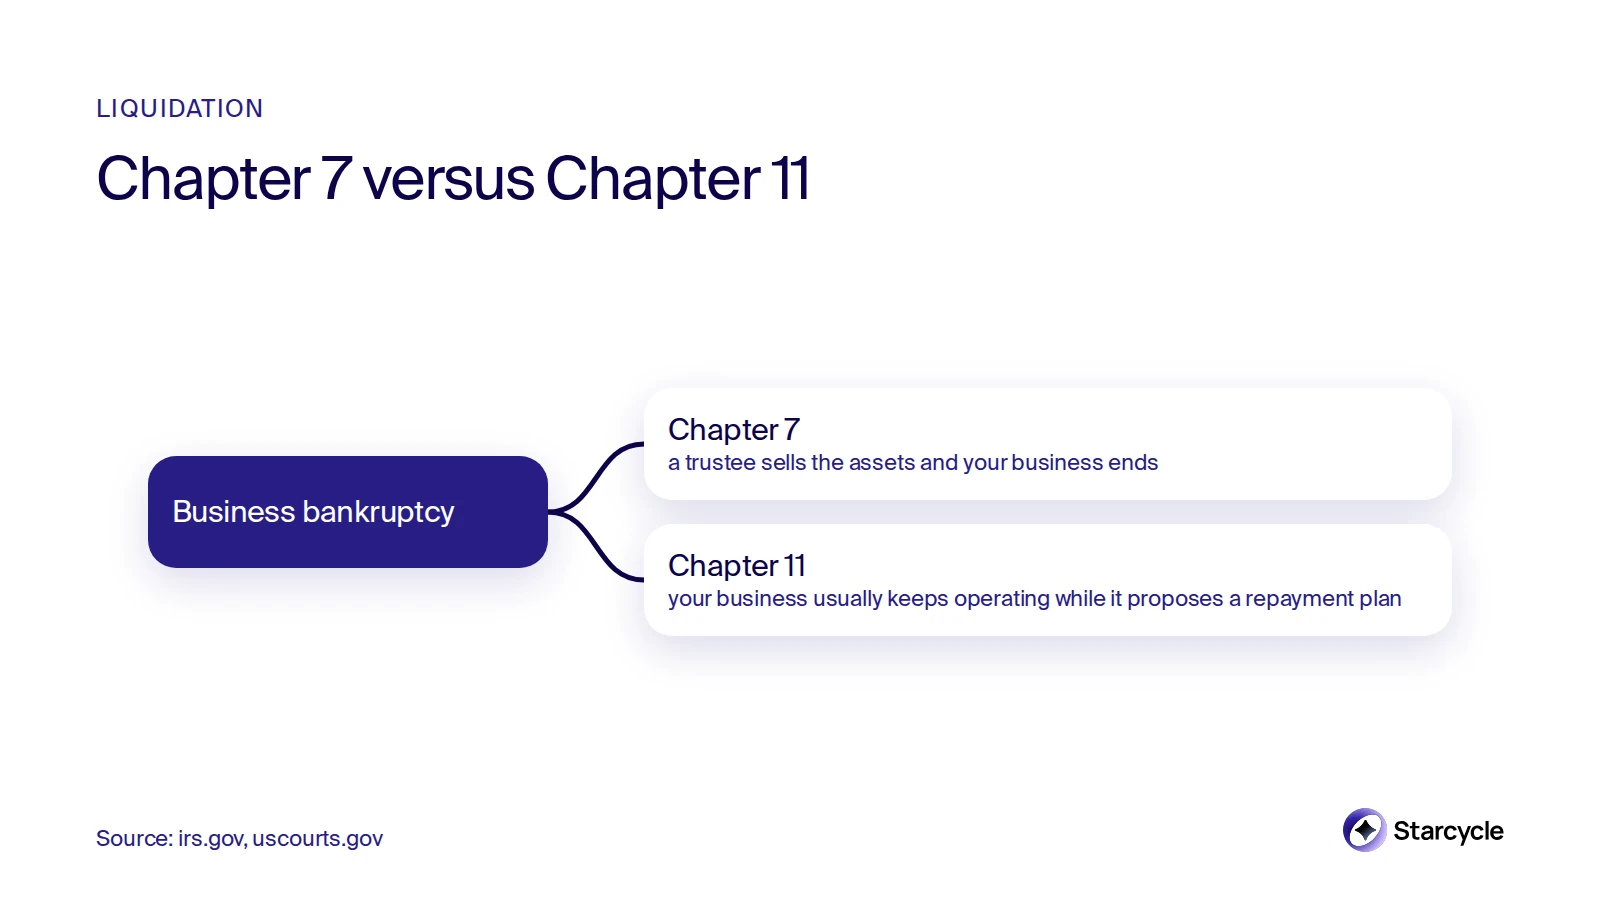
Business bankruptcy is a federal court case in which a company that can't pay its debts either liquidates or reorganizes. Partnerships and corporations file under Chapter 7 or Chapter 11. In Chapter 7 a trustee sells the assets and your business ends. In Chapter 11 your business usually keeps operating while it proposes a repayment plan.
The two chapters work like this:
Business filings are a small share of the total. The Administrative Office of the U.S. Courts counted 26,941 business bankruptcy filings in the year ending June 30, 2026, up 16.9 percent from 23,043 the year before, out of 608,511 filings overall. Chapter 11 also has a faster track for small business debtors called Subchapter V, and we've written about what Subchapter V filings show.
Filing a petition triggers the automatic stay, which stops most collection actions against your business and its property. It arises by operation of law, with no hearing needed, and that breathing room is what separates bankruptcy from simply being unable to pay bills. In a Chapter 11 case the stay suspends judgments, collection activities, foreclosures and repossessions on debts that arose before the filing. Outside bankruptcy there is no stay, so each of your creditors keeps its ordinary right to collect. Several can pursue their own collection at the same time, racing to recover what they're owed. Bankruptcy brings those competing claims into a single case with rules about who gets paid and in what order.
A bankruptcy case opens with a petition and a set of financial disclosures. Alongside the petition, the business files:
The next stage depends on the chapter. In Chapter 7 the case trustee then holds a meeting of creditors between 21 and 40 days after the petition is filed. In Chapter 11 the company files a disclosure statement and a plan. Creditors whose rights are affected vote on it, and the court holds a hearing to decide whether to confirm it.
Liquidation outside bankruptcy is run by you and your company under state law, with no court and no pause on collection. Bankruptcy is run under federal law with a judge, a trustee or a debtor in possession, and an automatic stay. Knowing the difference lets you weigh the two with your lawyer on your company's situation, rather than on which word sounds less intimidating.
Liquidation outside bankruptcy | Chapter 7 bankruptcy | Chapter 11 bankruptcy | |
|---|---|---|---|
What it is | Selling assets and paying debts as part of a wind-down | A liquidation run through federal court | A reorganization, or sometimes a liquidating plan |
Governing law | Your state's business statute | Federal Bankruptcy Code | Federal Bankruptcy Code |
Who starts it | The owners, by vote | The business, or its creditors by involuntary petition | The business, or its creditors by involuntary petition |
Who controls the process | The company's own managers or directors | A case trustee appointed by the U.S. trustee | The company as debtor in possession, monitored by the U.S. trustee |
Court involvement | None in the ordinary case | Bankruptcy court | Bankruptcy court, which must confirm the plan |
Collection by creditors | Continues | Stopped by the automatic stay | Stopped by the automatic stay |
How creditors are paid | In the order state law sets, before owners | By class: each class paid in full before the next | Under the confirmed plan |
What happens to the business | It closes | It closes | It usually continues |
Federal filing fees | None | $335 | $1,738 |
In a state-law liquidation you keep control. Your managers or directors decide what to sell, when, and to whom, within the limits of state law and your own governing documents. In Chapter 7 that control passes to the case trustee. The court may even authorize the trustee to operate the business for a limited time if doing so helps creditors. Bankruptcy is both relieving and restrictive: the automatic stay stops constant creditor pressure, but court oversight limits how freely the business can be run.
Chapter 11 sits between the two. The company keeps running the business as debtor in possession and files operating reports with the U.S. trustee. It also works alongside a creditors' committee, which ordinarily consists of the holders of the seven largest unsecured claims.
Outside bankruptcy, the company pays its creditors in the order state law sets, and each one can still send you demand letters or sue. In Chapter 7 the trustee pays them by class. The Bankruptcy Code sets six classes of claims, and each class must be paid in full before the next lower class is paid anything. Those distributions are subject to the rights of secured creditors, who hold collateral for what they're owed.
In Chapter 11, your creditors are paid according to the plan. Those whose claims are impaired, meaning they'll be paid less than the full value or on changed terms, vote on it by ballot.
Owners are last in line on every path. In a state-law liquidation you receive what remains after the creditors are paid or provided for. In Chapter 7 the debtor is only paid if all the other classes of claims have been paid in full.
How far a business case reaches into your own finances depends on the entity. On this point the U.S. Courts say that a corporation's Chapter 11 case does not put the stockholders' personal assets at risk beyond the value of their stock. A bankruptcy case involving a sole proprietorship, they say, includes both the business and personal assets of the owner. Anything you signed personally, such as a business loan or a lease, is a question to put to your lawyer.
The federal fees are fixed. A Chapter 7 case costs $335 to file: a $245 case filing fee, a $75 miscellaneous administrative fee and a $15 trustee surcharge. A Chapter 11 case costs $1,738: a $1,167 case filing fee and a $571 miscellaneous administrative fee. On top of that comes a quarterly fee to the U.S. trustee, which ranges from $325 to $30,000 depending on what the business pays out.
A state-law liquidation has no federal filing fee, so you pay only your state's dissolution fee. Your lawyer's and accountant's fees come on top on every path, and we break those down in the cost of shutting down a business.

75% of closures leave unresolved obligations that create long-term exposure. A structured winddown saves 40–60 hours and cuts legal risk ~80%.
Get a quoteDissolution is the legal step that ends your company as an entity, made by a vote of the owners and a filing with your state. Liquidation is the financial work of selling assets and paying debts. When you close a business you normally do both, and neither one is a bankruptcy.
It's natural to think the company is closed once the last asset is sold and the last bill paid. The entity ends only with dissolution, the owners' vote and the filing with your state. Seen in order, closing your business is the whole project, dissolving it is the state filing, and liquidating it is the money. The filings differ by entity, so we cover them in separate guides to dissolving an LLC and dissolving a corporation.
The IRS treats the two together. A corporation that adopts a resolution or plan to dissolve or to liquidate any of its stock files Form 966, Corporate Dissolution or Liquidation, within 30 days after the date the resolution or plan is adopted. Confirm the full list of final filings with your CPA.
The work piles up at this stage, with state filings, final returns, account closures and cancellations in several places at once. If you're evaluating a service to take on part of it, Starcycle prepares and files the state dissolution paperwork for U.S. companies. It also tracks your key dates and your contract and subscription cancellation timelines, and keeps the documents in one place. Final returns are coordinated with a partner CPA or your own.
A bankruptcy lawyer is the person to help you choose. Deciding between a state-law liquidation and a bankruptcy filing turns on your debts, your creditors and what you've signed, and that's legal advice on your specific position. This page can describe the two paths, and a lawyer who knows your facts tells you which one applies.
The federal courts say the same about filing. Their guidance on filing without an attorney strongly recommends seeking the advice of a qualified attorney, because bankruptcy has long-term financial and legal outcomes.

It's an easy call to put off. The first conversation goes faster when you already know what you owe and what you have, and whether your creditors are cooperating or demanding payment. The disclosures a bankruptcy court asks for are a good guide to what any lawyer will want to see, whichever path you end up on:
Tax follows your business into either path. The IRS points filers to Publication 908, its Bankruptcy Tax Guide, and it's worth walking through the final returns with your CPA before you commit to a timeline.
Liquidation is about the assets and bankruptcy is about the court, and your business can go through one, both or neither on its way to closing. Choosing the path and carrying it out are separate jobs, and a closure can stall in the gap between knowing what needs to happen and making it happen. Whichever path applies to you, your company still has to be closed with the state, the IRS and everyone it holds an account with.
Nobody plans for this part, and it tends to land in a week that's already full. When your path is set, we'd be glad to take part of the wind-down off your plate. We prepare and file the state dissolution paperwork, track your key dates and keep your documents in one place. We can also make intros to lawyers and accountants, including for the bankruptcy question above.
Yes. Under the U.S. Courts' description of Chapter 7 eligibility, the debtor may be an individual, a partnership, or a corporation or other business entity. The courts' filing guidance names LLCs among the nonindividual filers that use the forms numbered in the 200 series.
A business files a petition with the bankruptcy court serving the area where it is organized or has its principal place of business or principal assets. The petition goes in with the schedules listed above and the filing fee, which is paid to the clerk of the court. A bankruptcy lawyer prepares these with you.
The everyday terms are closing, shutting down or winding down. The legal terms name parts of that: dissolution for ending the entity with the state, liquidation for selling the assets and paying the debts, and bankruptcy for a federal court case over debts the business can't pay.