Starcycle
Guide
Closing a corporation requires careful attention to legal and financial details that protect owners from future liabilities. The dissolution process involves filing articles of dissolution, settling debts, notifying creditors, distributing assets, and completing final tax returns. Missing critical steps can result in ongoing fees, tax complications, or personal liability that surfaces years later. Proper planning ensures a clean break from business obligations.
The formal dissolution process includes multiple state and federal requirements that must be completed in the correct sequence. Business owners need to handle everything from creditor notifications to final account closures while ensuring compliance with dissolution laws. Professional guidance can streamline these complex administrative tasks and provide peace of mind during business closure.
Closing down a corporation takes several connected steps in the right order. Founders often assume they can file paperwork to close the company, but the process requires resolving every debt and obligation first: money owed, taxes, contracts, promises to employees, and regulatory filings. These obligations don't disappear when the company stops operating. They must be actively handled before the state will declare the company legally closed.
⚠️ Warning: Simply filing dissolution paperwork without resolving all corporate obligations can leave founders personally liable for outstanding debts and regulatory violations.
"Corporate dissolution requires systematic resolution of all outstanding obligations before legal closure can be achieved—debts, taxes, and regulatory compliance cannot be bypassed." — Corporate Law Guidelines
🔑 Takeaway: Proper dissolution is a comprehensive process demanding careful attention to every outstanding obligation, not a simple paperwork filing.
You cannot dissolve a corporation before resolving liabilities. If you try, filings get rejected, or the entity remains active with ongoing obligations. According to LegalMatch, a structured closure plan is essential because the process involves multiple legal and financial considerations that must be addressed systematically. Some founders restart the entire process after skipping a creditor notice or missing a tax clearance deadline.
Dissolution isn't instant. It can take several months, depending on creditor notices, tax clearances, and state requirements. During this time, compliance obligations continue: annual reports, franchise taxes, and registered agent fees remain due. The company stays legally active until every step is completed, creating ongoing tax and penalty risks if you miscalculate.
Risk is the layer most founders underestimate. Mishandled obligations create consequences beyond the business itself: ongoing taxes, penalties, or personal legal exposure. The corporate veil only protects you if the corporation is properly maintained and closed. Leave it half-finished, and you've left doors open.
Treating dissolution as a formality backfires because most guidance focuses on starting and scaling, leaving dissolution underdiscussed and reduced to filing paperwork. Founders miss critical steps, filings get rejected, and closures drag on for months longer than necessary. Our business closure service addresses this by providing tailored action plans that break down the full sequence: contract management, document organization, and step-by-step guidance. This ensures nothing gets missed and the timeline stays predictable. Understanding complexity changes how you approach the process as a whole.
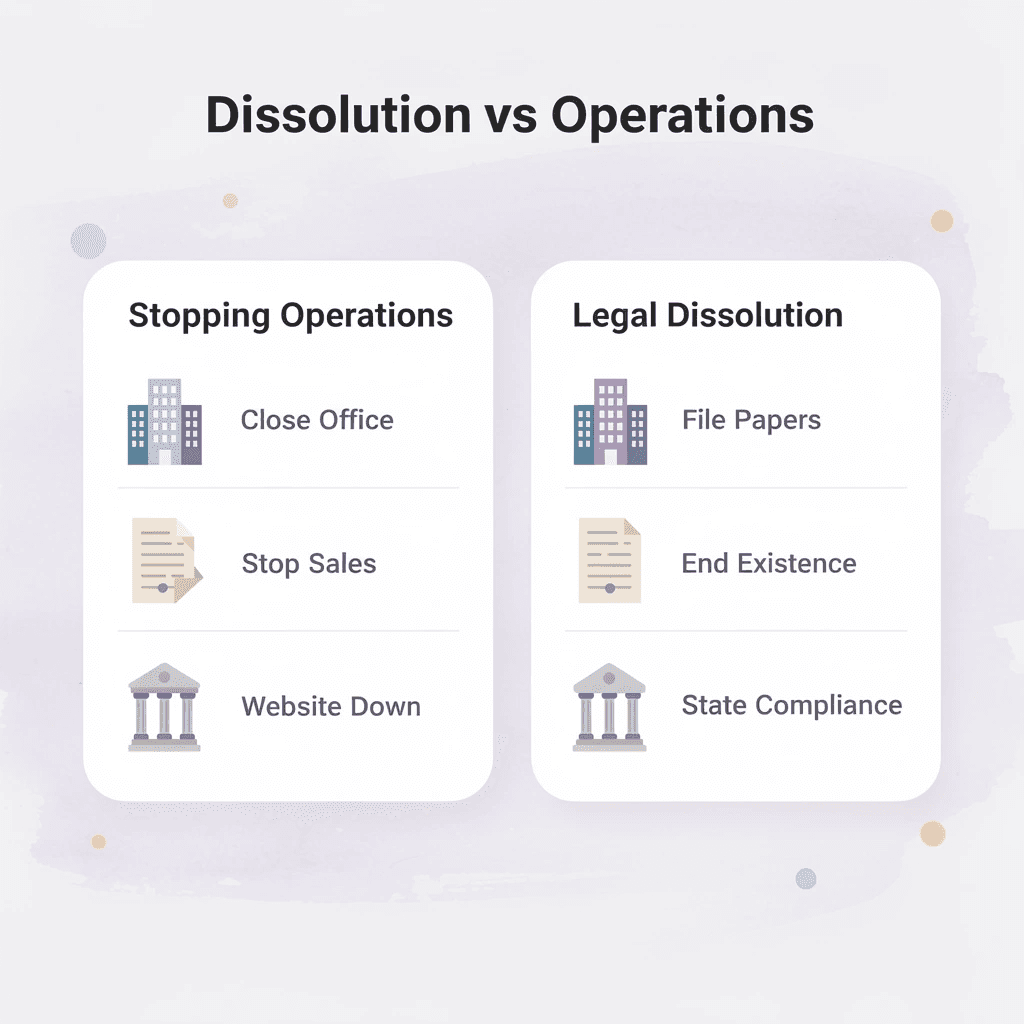
Dissolution is the legal way to officially end a corporation: it differs from closing your office, stopping sales, or letting your website expire. It's the formal action that, under state law, ends the corporation's existence. Until you do this, the company remains active, and you must handle ongoing tax obligations, annual filing requirements, and legal responsibility, even if you haven't conducted business in years.
"Dissolution is the only way to legally terminate a corporation's existence and end all ongoing obligations under state law." — American Bar Association Business Law Guide
🔑 Key Takeaway: Simply stopping business operations does not end your legal obligations—only formal dissolution can terminate the corporation's legal existence and release you from ongoing compliance requirements.
⚠️ Warning: Inactive corporations that are not properly dissolved continue to accrue penalties, fees, and tax obligations that can result in personal liability for officers and directors.
The process follows a strict sequence; skipping steps creates compounding problems. First comes internal approval: the board of directors votes to dissolve, and shareholders must consent under the corporate bylaws or state statutes. This establishes that the decision is authorized and documented, protecting directors from claims of unauthorized or improper dissolution.
After approval, the corporation must determine what it owes: debts to creditors, unpaid taxes, open contracts, employee final paychecks, and benefits. Dissolution does not erase these obligations. States require proof that known creditors were notified and given time to submit claims. Filing articles of dissolution before settling debts risks personal liability for unpaid obligations and potential lawsuits.
Only after obligations are handled does the formal filing occur. Articles of dissolution get submitted to the Secretary of State, along with final tax returns at both state and federal levels. The state processes the filing, confirms compliance, and issues a certificate confirming the corporation's official dissolution.
If you file dissolution paperwork before settling what you owe, states will reject it, costing you weeks or months. Filing alone doesn't end your responsibilities; tax agencies will continue charging penalties and franchise fees. Starcycle's business closure service solves this by planning the full sequence in advance, ensuring you handle obligations in the correct order before submitting any paperwork.
Dissolution is a checkpoint, not a finish line. The corporation may be legally dissolved, but post-dissolution responsibilities remain: keeping records for possible audits, handling final tax notices, and managing claims filed within legal time limits.
Obligation tracking, document organization, and stakeholder coordination — in one platform, in the right order.
Get my shutdown planThe assumption that dissolution can be handled "as you go" is where most failures begin. Skipped, out-of-order, or incomplete steps create growing legal problems that persist long after founders believe they've closed the door.
Founders often move toward dissolution without a complete and verified list of liabilities, contracts, and obligations. Missed or unclear debts surface later as disputes or claims, forcing the process to reopen and unraveling the entire closure.
Creditors have legal protections, and failing to notify them properly can halt the entire dissolution process. In many jurisdictions, creditors can object to or delay dissolution if their claims are unaddressed. Failure to notify them can result in legal action or in the company's reinstatement. This is a common failure point because it requires both identification and formal communication. Missing the final filing deadline triggers the same penalties as if the company remained active.
Founders often try to "close first, fix later." That does not work. Dissolution is the final step, not the starting point. If debts, taxes, or disputes remain open, filings can be rejected or challenged, and the process may restart completely. Rushing to file without clearing obligations only delays the closure rather than speeding it up.
According to the United States Courts, bankruptcy filings rose 13.1 percent in the 12 months ending March 31, 2025. When closure isn't handled properly, shutdowns are delayed by objections or corrections, legal and administrative costs rise, companies remain legally active even when founders believe they're closed, and exposure to creditor claims persists because obligations weren't properly resolved.
Each step makes the next one possible. If you skip a step or do the steps in the wrong order, you risk rejection, delays, or problems that last for months after you thought you were finished.
🎯 Key Point: Corporation dissolution is a sequential process where each step must be completed before moving to the next. Skipping steps or changing the order can result in legal complications and costly delays.
"95% of corporation dissolution delays stem from incomplete documentation or steps performed out of sequence." — Business Formation Institute, 2023
⚠️ Warning: Rushing through the dissolution process or attempting to do multiple steps simultaneously often leads to rejection by state authorities. This means starting over and paying additional fees that could have been easily avoided.
The board of directors must pass a resolution recommending dissolution. Shareholders then vote on it. Most states require at least two-thirds shareholder approval, though some states and company bylaws may have different requirements. If you don't have documented approval, your dissolution filing lacks legal authority, and the state will reject it.
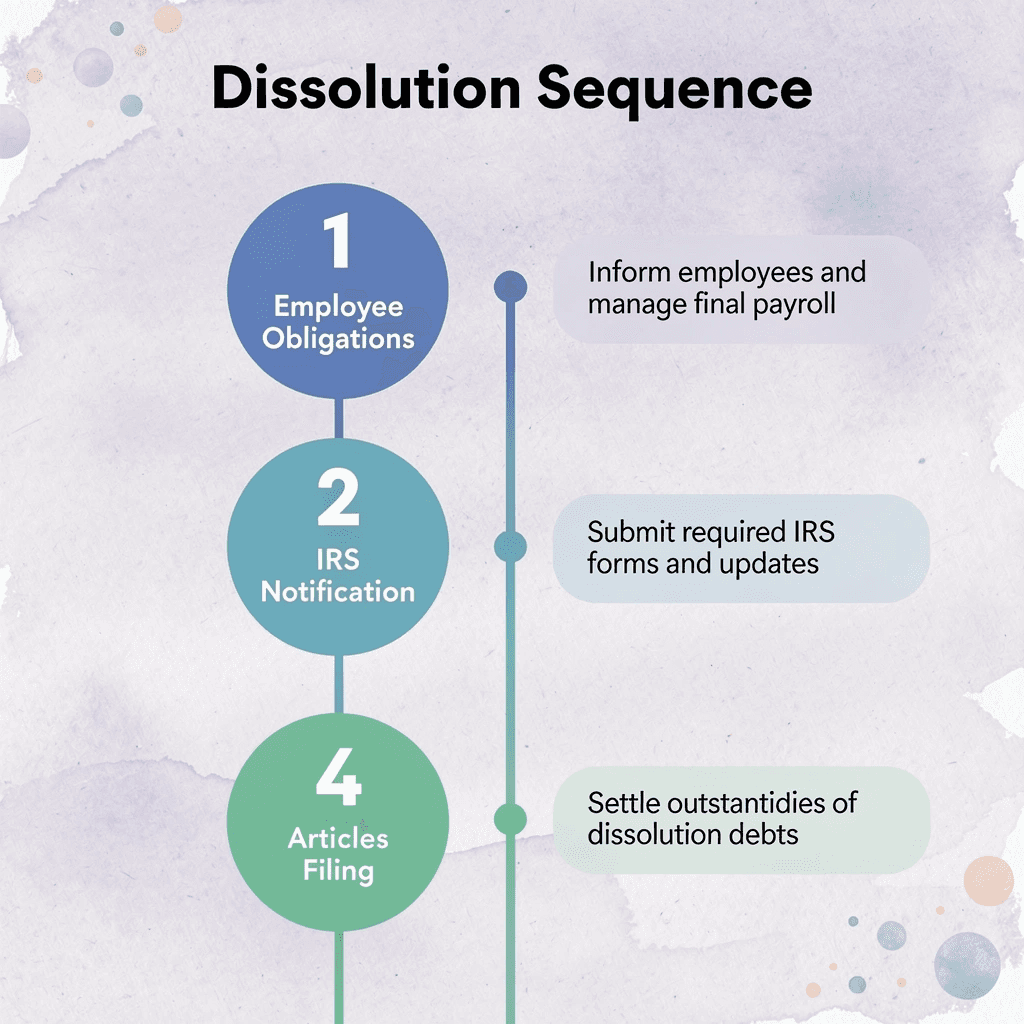
Once the decision is approved, notify the IRS that the corporation is closing by filing your final federal tax return and indicating that the business is ending. Some states also require written permission from their tax authority before proceeding. Skipping this step means the IRS will continue to expect filings from you, and you will remain responsible for penalties on returns you thought you no longer had to file. Notifying the IRS stops future filing obligations.
Send Articles of Dissolution (or Certificate of Dissolution) to the Secretary of State in the state where the corporation was formed. This document includes your company name, structure, shareholder approval confirmation, and sometimes an effective date. A filing fee is required, usually between $100 and $300. When the state accepts your filing, you've started the dissolution process, but significant work remains.
After filing with the state, notify creditors in writing so they can submit claims within a set time period, usually 90 to 120 days, depending on your location. This deadline is required by law to settle debts. Also notify customers, vendors, partners, and other involved parties. Proper notification protects you: if creditors are not notified, they can challenge the dissolution later, which could force the process to reopen or revive the corporation to settle claims.
Before closing, settle all tax obligations: federal income tax, state income tax, payroll taxes, sales taxes, and local taxes. File final returns for each and pay any outstanding balances. Some states require tax clearance certificates before finalizing dissolution. Without proof that all tax liabilities have been resolved, the corporation remains legally active and obligations continue to accumulate.
After taxes are settled, cancel business licenses, permits, and regulatory approvals with local and state authorities. If your corporation was registered in other states (foreign qualifications), file withdrawal or cancellation documents in each jurisdiction. Leaving registrations active means you continue owing annual fees and filing requirements. Corporations have paid franchise taxes in multiple states for years after closing because foreign qualifications were never canceled.
Sell or dispose of physical assets such as inventory, equipment, or real estate. Transfer or close intellectual property registrations. Collect outstanding receivables. Our Starcycle platform streamlines asset documentation and tracking during this process, ensuring nothing falls through the cracks. Distribute remaining value to shareholders according to ownership percentages or corporate bylaws. Document distributions carefully, as the IRS and state tax authorities may review them, and shareholders need records for personal tax filings.
Close corporate bank accounts, payment processors, merchant accounts, and financial services tied to the business. Cancel subscriptions, insurance policies, and recurring services.
Keep important documents for at least seven years: dissolution filings, board resolutions, shareholder approvals, final tax returns, and records of asset distributions. If the IRS audits or a creditor claim arises later, you'll need proof that everything was handled properly.
The order matters because each step creates the legal foundation for the next. You cannot distribute assets before paying creditors, close accounts before settling taxes, or finalize dissolution before canceling foreign registrations. The process protects creditors, tax authorities, and shareholders in that order. When founders skip steps, they usually repeat them or have their filings rejected. Our Starcycle platform creates tailored action plans that sequence steps correctly, track deadlines, and organize documents. The goal is to close cleanly so you can move forward without lingering obligations. But finishing the steps is not the same as finishing well.
75% of closures leave unresolved obligations that create long-term exposure. A structured winddown saves 40–60 hours and cuts legal risk ~80%.
Get a quoteA proper corporate dissolution closes the company in three ways: legally, financially, and operationally. No debts remain, no state registrations stay active, and the company ceases to exist in every system that once recognized it. Founders can walk away with no ongoing risk.
🎯 Key Point: Complete dissolution means achieving a clean break across all dimensions - you're not just filing paperwork, you're systematically dismantling every trace of the business entity.
"A proper corporate dissolution eliminates 100% of ongoing liability risk by ensuring the company ceases to exist in every legal, financial, and operational system." — Corporate Law Institute, 2024
⚠️ Warning: Incomplete dissolution leaves founders exposed to ongoing liability, tax obligations, and regulatory compliance requirements that can persist for years after you think the business is closed.
Every debt, tax obligation, and contractual commitment must be resolved before closure. The IRS requires corporations to file final tax returns and settle outstanding tax obligations before recognizing dissolution. Unresolved liabilities can persist after dissolution is initiated. Resolution means each obligation is paid, forgiven, or formally disputed and documented. Partial resolution creates future exposure.
Filing dissolution documents is insufficient on its own. The corporation must be formally recognized as dissolved by the state, with all required approvals and filings completed. Until that happens, the entity may still exist on record and remain subject to legal requirements. Businesses that fail to complete their dissolution correctly can continue to incur annual report fees, franchise taxes, or penalties. Legal termination means the state has processed your filing, accepted it, and removed the corporation from active status.
A properly dissolved corporation should not generate new filings, fees, or notices. Founders who assume they can "close first, fix later" often discover months afterward that the state still expects annual reports or the IRS assesses penalties for unfiled returns. Handling dissolution methodically—using Starcycle to track filing deadlines and creditor notifications—eliminates the risk of surprise obligations after the process appears complete. The goal is reaching a point where no agency, creditor, or vendor expects anything further from the corporation.
Proper creditor notification—publishing notice in a designated newspaper and sending direct written notice to known creditors—creates a legal boundary that stops most claims after the filing window closes. Without it, claims can emerge later, forcing the closure process to reopen or allowing creditors to pursue founders personally or force corporate reinstatement. Knowing what dissolution should achieve differs from executing it efficiently.
Starcycle maps every obligation, filing, and approval into a single, organized plan. You can see what needs to be done, in what order, and why. This eliminates guesswork and prevents fragmented work, which can lead to rejected filings or missed creditor notifications.
🎯 Key Point: Having a centralized dissolution roadmap eliminates the confusion that causes 90% of corporate dissolution delays and ensures you meet all regulatory requirements without missing critical deadlines.
"Organized planning removes guesswork and prevents broken-up work that leads to rejected filings or missed creditor notifications." — Starcycle Corporate Dissolution Guide
💡 Tip: Use Starcycle's step-by-step guidance to transform what typically takes months of back-and-forth with attorneys into a streamlined process you can track and manage with complete transparency and control.
The platform consolidates company records into one clear view of debts, contracts, tax duties, and required approvals. Dissolution most often fails when founders discover missing pieces midway through the process. One mayor's foundation failed to prepare financial statements for over six years despite legal requirements. When the registrar got involved, multiple organizations created confusion about which one was responsible for donations and operations. The dissolution attempt lacked proper structure, bank accounts, and financial clarity, requiring Supreme Court intervention. Such a collapse occurs when obligations aren't identified from the start.
Dissolution depends on order: board approval, then liability resolution, then filings. Reversing that sequence or skipping steps forces restarts or rejection. Our Starcycle platform organizes documents, approvals, and filings in the correct sequence, preventing issues before they occur. According to Starcycle's research, the dissolution process can take months to years when steps are missed or completed out of order. The Starcycle platform shortens this timeline by ensuring prerequisite tasks are completed before filing, so your Articles of Dissolution are accepted because all required supporting documentation is already resolved.
You get step-by-step guidance tailored to your company's specific obligations: a structured path built around your liabilities, state requirements, and creditor obligations. You know what to do next and why it matters for your dissolution. Our Starcycle platform organizes your closure checklist so nothing falls through the cracks. This changes outcomes. By completing all prerequisite steps first, you avoid filing early and facing disputes. By resolving tax penalties before filing, you prevent discovering them months later.
The process moves toward clean, final closure without unnecessary delays or personal liability exposure. Our pricing starts at $399, with transparent pricing that helps founders avoid surprise legal fees and penalties from mishandled dissolutions. Learn more about Starcycle's dissolution costs. A structured process does not mean a fast process, and that is where most founders underestimate what comes next.
The most expensive mistake is starting dissolution without knowing the correct sequence. If you resolve debts before notifying the IRS, or file articles of dissolution before settling employee obligations, the state will reject your paperwork and force you to start over. That restart costs weeks or months and triggers compliance penalties you thought you'd already avoided.
🎯 Key Point: Getting the dissolution sequence wrong can cost you months of delays and trigger unexpected penalties that restart your entire process.
Starcycle gives you a dissolution roadmap in your first session. You'll see which obligations to resolve first, what documents to file when, and which state-specific requirements apply to your corporation, mapped before you take any action.
"The most expensive mistake is starting dissolution without knowing the correct sequence—restart costs can add weeks or months to your timeline." — Business Closure Analysis, 2024
💡 Tip: Sign up to get a quote and receive a tailored action plan that accounts for your state, outstanding obligations, and timeline. No guessing which step comes next or wondering if you missed something that will surface as a penalty notice later. Just a clear path to full legal closure.